Exploring Income Opportunities for People With Disabilities
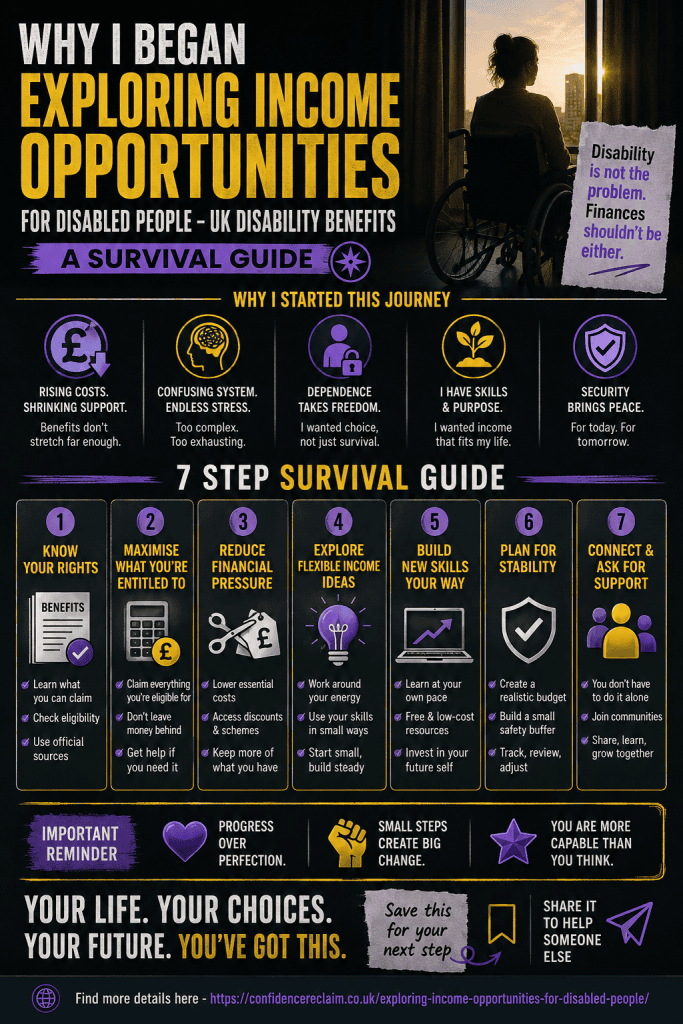
Why I Began Exploring Income Opportunities for Disabled People
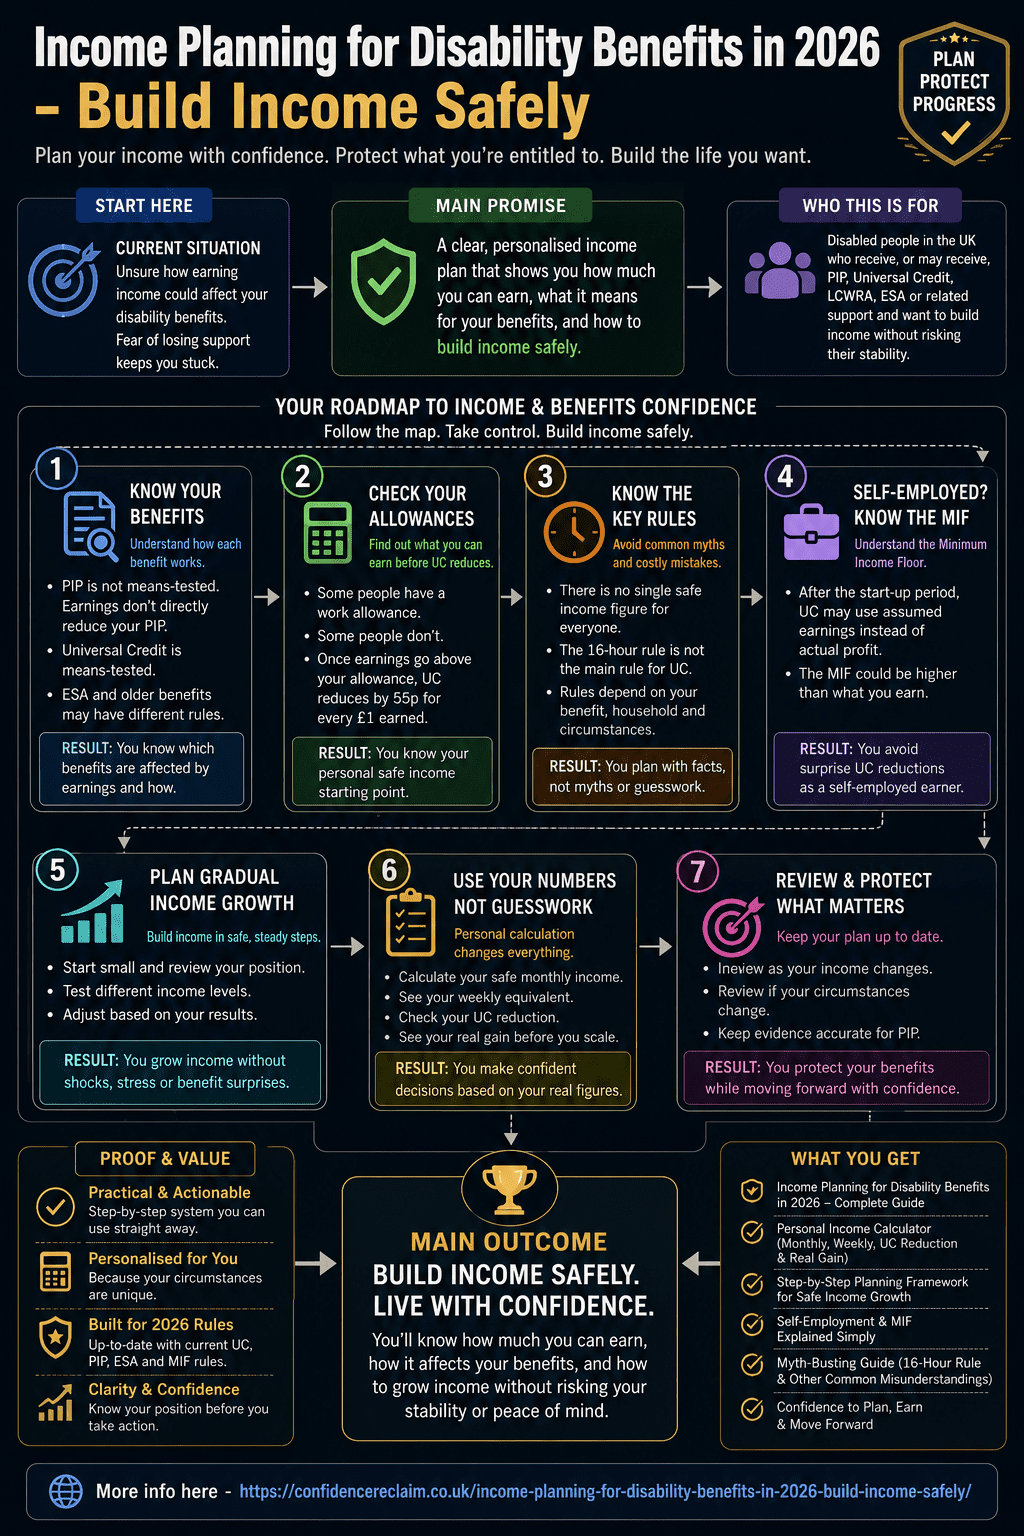
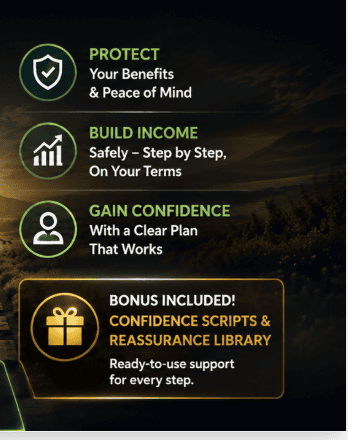
Save this handy info graphic for when you need it
Save this handy info graphic for when you need it
The Confidence Reclaim Starter Pack is a guided starting point for disabled people and people with long-term health conditions in the UK who want to explore earning extra income.
It helps users understand their personal benefits position before introducing a flexible online income opportunity and the practical steps needed to begin.
The aim is to replace confusion and rushed decisions with a calmer, graduated pathway toward action.
The Confidence Reclaim Starter Pack is a guided starting point for disabled people and people with long-term health conditions in the UK who want to explore earning extra income.
I created it for people who have ambition, curiosity or a need for more financial breathing space, but feel uncertain about what they can safely and realistically do.
It combines three things that are often treated separately:
The Starter Pack is not simply a list of possible jobs or money-making ideas.
It is a structured pathway.
It helps you slow the process down, ask the right questions and take one step at a time. The aim is to replace guessing and fear with clearer information, practical action and greater control over your next decision.
I know what it feels like when disability changes your working life, income, confidence and sense of control.
One minute, the way you work makes sense.
Then your health changes.
What you can do changes. Your income may become less certain. Everyday decisions can start to feel heavier than they did before.
You are not only dealing with the effects of disability. You may also be dealing with benefit rules, assessments, paperwork, financial pressure and a difficult question:
I found that a great deal of information explains benefit rules, what someone may be able to claim and what they must report.
That information matters.
But once you have read it, the personal question can remain unanswered:
That is the gap I created The Confidence Reclaim Starter Pack to address.
My aim is not to push disabled people into work.
It is not to suggest that every person can work, should work or must turn themselves into a business owner.
It is for people who already want to explore change and need a calmer, more structured way to begin.
The Confidence Reclaim Starter Pack may be suitable for you when:
Many disabled people cannot promise that every day will be the same.
There may be good days, bad days and days when very little is possible.
That means an opportunity should fit around the person. The person should not have to force their health around the opportunity.
The Starter Pack is not designed to persuade someone who does not want to explore income.
It is not a promise of guaranteed earnings.
It does not guarantee that benefits will remain unchanged.
It is not a replacement for qualified welfare rights, legal, financial, tax or benefits advice.
It is also not an instant route to financial independence. It provides a starting structure, planning tools and practical actions. The results will depend on the person, the time they can contribute, the actions they take and their individual circumstances.
There is no single income figure that is safe or appropriate for everyone.
Benefits, household circumstances, existing awards, housing support, health status and the type of income being considered may all affect the position. This is why personal checking matters before decisions are made.
The Starter Pack uses a two-stage approach.
The first stage begins before you try to earn anything.
It helps you look at your current circumstances and ask the questions that apply to you.
Different benefits have different conditions. Two people with similar disabilities may have different household circumstances, different awards and different considerations.
The Safe Income Planner helps you organise the relevant information and develop a clearer view of your own position.
The Graduated Income Plan then helps you think in steps rather than treating income as an all-or-nothing decision.
The purpose is not to produce a universal answer.
It is to help you move from vague worry toward a more informed personal plan.
You should still check your conclusions with an appropriate adviser before making decisions that could affect your benefits or financial position.
Only after considering your position does the Starter Pack introduce the online income opportunity.
The opportunity involves promoting useful offers to people who may benefit from them.
The basic idea is familiar.
Most of us have recommended a film, product, service, restaurant or useful resource to someone. Online offer promotion develops that everyday act of recommendation into a structured activity.
The external platform is introduced inside the course.
I have chosen not to name it on this page.
That is deliberate.
Searching for the platform independently can lead people into a large amount of information before they understand the correct setup process. Important steps can be missed and the person can lose sight of what they were originally trying to achieve.
The Starter Pack introduces the platform at the appropriate stage. It then helps the user work through the setup process, prepare to receive payments and begin creating their first opportunity.
This matters because completing the steps produces something more valuable than passive information.
It gets the user moving.
A person is no longer only reading about change. They are taking positive action toward it.
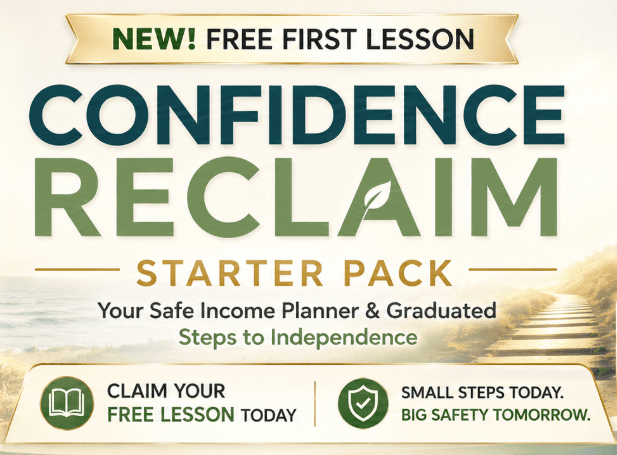
The current Starter Pack includes:
This introductory lesson is designed for people who feel cautious, stuck or afraid of losing something they depend on.
It explains how the mind can begin treating feared predictions as though they are proven facts. It introduces simple ways to separate a forecast from evidence and begin approaching decisions from a calmer place.
The roadmap helps the user understand the sequence of the course and what each stage is intended to achieve.
This planning tool helps users organise information about their position and consider how additional income might interact with their existing circumstances.
It is a planning aid, not a benefits decision or guarantee.
The Graduated Income Plan encourages measured progression.
Instead of assuming someone must make one large decision, it helps them think through smaller stages. The user can review what is happening, build experience and decide what to do next from a more informed position.
The course takes the user through the actions needed to access the opportunity, easily set up the relevant structure and prepare to receive payments.
The external platform and personal invitation are provided at the appropriate point in the course.
The Starter Pack explains where offers come from, how the promotion model works and how a user can begin setting up an initial offer.
This can remove one of the biggest barriers faced by someone who does not feel business-minded.
You do not have to begin by inventing an entirely new company, developing a product from nothing or trying to work out what to sell. The opportunity already provides offers that can be explored and promoted.
The assessment tool guides users through questions that may help them understand whether Access to Work support grant could be relevant to their circumstances.
It is intended to make the initial exploration clearer and less overwhelming. It does not make an official eligibility decision.
This library provides practical support for moments when confidence starts to wobble.
It is designed to help the user return to the facts, remember why they began and continue without turning temporary uncertainty into a final decision.
The course itself can take approximately one hour to complete.
There is no requirement to finish it in one sitting.
You can divide it into smaller sections and work through it according to your energy and capacity. There is no fixed timetable.
The purpose of the structure is to reduce the time and confusion involved in trying to find, compare and organise all the relevant information independently.
The underlying research and setup can be completed without the Starter Pack. However, the course material estimates that finding the correct route and working through the setup independently could take several days, with a greater chance of overlooking an important step.
The Confidence Reclaim Starter Pack is not the only possible route to additional income.
Someone might consider surveys, blogging, reselling products, freelance services, remote employment or other online opportunities.
The right comparison is not simply:
A more useful comparison considers whether the opportunity fits the person’s actual life.
Comparison question | Why it matters | The Confidence Reclaim approach |
Can it fit around changing health? | Fixed schedules may not suit fluctuating capacity. | The pathway can be followed gradually and at the user’s pace. |
How complicated is the setup? | Too many disconnected steps can create confusion. | The course organises setup into a guided sequence. |
Is a new business idea required? | Inventing a product or service can become an immediate barrier. | Existing offers can be explored before creating original offer combinations. |
Is the work paid once or can it keep producing value? | Some tasks end as soon as payment is received. | An offer created within the platform may continue working after the initial setup. |
What physical demands are involved? | Mobility, pain and fatigue may rule out some activities. | The opportunity is primarily online. |
How quickly can someone begin taking action? | Endless research can delay progress. | The Starter Pack focuses on getting the user organised and ready to act. |
Does it include benefits planning? | Income cannot be considered separately from individual circumstances. | The Safe Income Planner and Graduated Income Plan come before scaling activity. |
Is specialist business experience required? | Many people have ambition without a business background. | The course explains the process from the beginning. |
What support is available when confidence drops? | Fear can interrupt action even when the practical route is clear. | The free lesson and reassurance resources address this directly. |
This framework will also be used in separate articles comparing the Starter Pack with individual opportunities.
Each comparison should consider both advantages and disadvantages.
The purpose is not to declare that one route is automatically best for everyone. It is to help disabled people judge opportunities against their health, circumstances, goals and tolerance for uncertainty.
A great deal of disability income content starts and ends with regulations or a short list of ideas.
The Confidence Reclaim Starter Pack goes further.
It connects understanding with action.
It helps the user consider their personal position, introduces a specific opportunity and guides them through the practical steps needed to begin.
That is the central difference.
Information can tell you that options exist.
A pathway helps you take the next step.
You do not have to decide everything today.
You do not need to prove anything to anyone.
You can begin by understanding why I created The Confidence Reclaim Starter Pack and what I experienced when disability changed my own working life.
Read my story and learn why I created Confidence Reclaim
From there, you can decide whether the next step feels right for you.
The Confidence Reclaim Starter Pack provides guidance, structure and educational tools. It does not replace qualified welfare rights, legal, financial, tax or benefits advice. Always check your own circumstances carefully before making decisions.
If you are ready to find out more about this exciting opportunity – Read my story and learn why I created Confidence Reclaim
The Confidence Reclaim Starter Pack is a guided course and set of planning tools for disabled people and people with long-term health conditions in the UK who want to explore earning extra income.
It helps users begin by considering their own benefits position. It then introduces a flexible online income opportunity and guides them through the practical steps needed to get set up and ready to receive payments.
It is designed to turn information into positive action, one manageable step at a time.
The Starter Pack is for people who want to explore additional income but need an approach that can fit around disability, fluctuating health, fatigue, pain, appointments or changing capacity.
It may also suit someone who has ambition but does not consider themselves business-minded.
The course does not assume that every disabled person can work or should be encouraged into work. It is for people who already want to explore change and would benefit from a calmer, more structured starting point.
No.
The Confidence Reclaim Starter Pack provides educational guidance, planning tools and a structure for asking the right questions.
It does not replace qualified welfare rights, legal, financial, tax or benefits advice. Users should always check their own circumstances before making decisions that could affect their income or benefits.
No.
There is no single safe income figure that applies to everyone.
The effect of earnings may depend on the benefits you receive, your household circumstances, housing support, existing awards and whether the income comes from employment or self-employment.
The Safe Income Planner and Graduated Income Plan are designed to help you understand the questions that apply to your situation. They do not guarantee a particular benefits outcome.
No previous business experience is required.
One of the biggest barriers to starting something independently is deciding what to offer, how to set it up and how payments will work.
The Starter Pack breaks the process into practical steps. The external platform already contains offers that users can explore, which means they do not have to begin by inventing a completely new product or business idea.
The platform is introduced inside the course at the stage when the user is ready to set it up correctly.
This is deliberate.
Searching for the platform too early can lead someone into a large amount of disconnected information. They may miss an important step, become overwhelmed or lose sight of what they were originally trying to achieve.
The Starter Pack is designed to guide the user through the correct sequence, prepare them to receive payments and help them begin taking practical action in the shortest reasonable time.
The current Starter Pack includes:
The course also provides access to the external platform at the appropriate stage.
The Prediction Trap is the free introductory lesson.
It is designed to help people notice when fear is being treated as proof. It explains how the mind can predict a negative outcome before all the facts are known and introduces simple ways to separate a forecast from evidence.
The lesson provides a calm first step before the practical income planning and setup stages begin.
The course can take approximately one hour to complete.
You do not have to complete it in one sitting.
You can work through it in smaller sections, according to your health, energy and available time. There is no fixed deadline.
The course was designed with fluctuating health in mind.
Many disabled people cannot commit to fixed hours or guarantee the same level of capacity every day. The Starter Pack allows users to move through the material and explore the opportunity at their own pace.
The aim is for the process to fit around the person, rather than forcing the person to fit around a rigid schedule.
No.
The Starter Pack provides guidance, planning tools, access to an opportunity and practical setup steps.
It cannot guarantee income. Results will depend on the user’s circumstances, the actions they take, the time they can contribute and how they apply what they learn.
The purpose is to help someone begin from a clearer and better-prepared position.
Some income activities involve completing one task and receiving one payment.
The opportunity introduced through the Starter Pack allows users to create an element within the platform that may continue working after the initial setup. This creates the possibility of building activity over time rather than starting again from zero for every payment.
That does not make it automatically better for every person. Any opportunity should be compared according to flexibility, setup requirements, physical demands, earning potential and how well it fits the person’s circumstances.
A good first step is to read the founder’s story.
It explains why I created The Confidence Reclaim Starter Pack, what I experienced when disability changed my own working life and why I believe people need a calm pathway rather than more pressure.
From there, you can decide whether to explore the free lesson or the full Starter Pack.
Income Planning For Disability Benefits
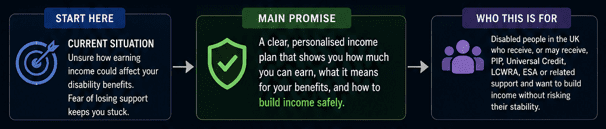
This guide is for disabled people in the UK who receive, or may receive, PIP, Universal Credit, LCWRA, ESA or related support and want to understand how earned income could affect their benefit position.
It is also for people who are thinking about part-time work, self-employment, increasing hours, changing rates or testing income after a period of illness or disability.
The aim is simple.
To help you plan income without guessing.
This guide covers
This guide covers Universal Credit, PIP, LCWRA, ESA transition, self-employment, the Minimum Income Floor and safe income planning.
It explains how earned income may affect your benefit position before you increase work, hours or self-employed income.
For your own figures, use the Confidence Reclaim Starter Pack calculator.
Planning income around UK disability benefits is not about avoiding work.
It is about avoiding guesswork.
For many disabled people, the hardest part is not motivation.
It is not ambition.
It is not the desire to move forward.
The hardest part is knowing where the line is.
Earn too little and nothing really changes.
Earn more without checking and it can feel like everything is at risk.
That uncertainty keeps people stuck. It is part of the benefits trap.
The benefit system in 2026 is more personal than it used to be.
Your safe income position depends on your actual circumstances, not one general figure copied from an article, calculator or advice forum.
That is why income planning now needs to start with your own numbers.
The Confidence Reclaim Starter Pack is built around that idea.
It helps you map your income gradually, test different earning levels and understand how your Universal Credit may change before you take bigger steps.
Income Planning For Disability Benefits
One of the biggest mistakes people make is treating all disability benefits as if they follow the same rules.
They do not.
Personal Independence Payment, Universal Credit, ESA, Carer’s Allowance and other linked support all work differently.
Some are affected by earnings.
Some are not directly affected by earnings.
Some may be affected by changes in your health, care needs, household or work pattern.
That difference matters.
A safe income plan starts by knowing which benefit you receive and how that benefit reacts when your income changes. Avoid the benefits trap.
PIP stands for Personal Independence Payment.
It is not means-tested.
That means your earnings do not directly reduce your PIP award.
You can earn income through employment or self-employment without your PIP being reduced simply because you earned money.
But PIP is still based on how your condition affects your daily living and mobility.
That means work can create an indirect risk if it appears inconsistent with the needs described in your PIP award.
For example, if your award is based on difficulty preparing food, managing journeys or moving around, and your work appears to contradict that evidence, it could raise questions at review.
That does not mean work is forbidden.
It means your evidence needs to stay accurate.
If your needs have not changed, keep records that show that.
If your needs have changed, get advice before you make decisions that rely on your current award staying the same.
Universal Credit is means-tested.
That means earnings can affect how much you receive.
If you have a work allowance, you may be able to earn up to that allowance before your UC reduces.
If you do not have a work allowance, your UC may reduce as soon as your earnings are counted.
Once the taper applies, Universal Credit usually reduces by 55p for every £1 of earnings above your relevant allowance.
That is not a cliff edge.
It is a gradual reduction.
But it still changes your monthly position.
This is why your own calculator matters.
You need to know whether you have a work allowance, where that allowance sits and what happens if you earn above it.
Many people are moving from older benefits to Universal Credit.
But not everyone has moved yet.
If you are still on Employment and Support Allowance, the rules may be different.
Hours rules, permitted work rules and earnings limits may still apply.
Do not assume UC rules apply to you until you know what benefit you are actually on.
If you are still on ESA or transitioning, check with a benefits adviser before starting work, increasing hours or becoming self-employed.
Many people still believe they must stay under 16 hours a week.
For Universal Credit, that is not the main rule.
UC is based mainly on income and household circumstances, not a fixed 16-hour limit.
What matters is how much you earn and how those earnings affect your UC calculation.
This is a major shift.
The old question was:
“How many hours can I work?”
The better question is:
“What level of income is safe for me?”
There is one important warning.
If you are still on ESA or another older benefit, hours rules may still matter.
So the safest wording is this:
For Universal Credit, focus on income.
For ESA or older benefits, check the hours rules before making changes.
Work, PIP and reviews: what “Right to Try” does and does not protect
From 30 April 2026, paid work or voluntary work should not, by itself, be treated as a reason to trigger a PIP award review or a Work Capability Assessment reassessment.
This is sometimes described as a “Right to Try” work protection.
But it is not a guarantee that work can never lead to questions about your award.
The DWP can still look at the type of work you are doing. If the work appears to suggest that your functional ability has changed, or that your previous award may no longer reflect your needs, it may still lead to a PIP review or WCA reassessment.
For example, work that appears inconsistent with the difficulties described in your PIP award, LCW or LCWRA decision may create risk. Work that is clearly adapted around your condition, supported by adjustments or consistent with your limitations may carry less risk.
This does not mean disabled people should avoid work. It means work should be planned carefully. Keep records of your limits, adjustments, support, reduced hours, rest periods and any help you need to do the work safely.
If your condition or daily living needs have changed, get advice before relying on your existing award.
Work alone should not trigger a review, but work that appears inconsistent with your award may still raise questions.
If your needs have not changed, make sure your records explain how the work is possible despite your condition.
The word in a few conversations recently, where people are talking quietly about the DWP’s “Right To Try” situation.
Not panic talk.
More like the kind of careful, experienced advice you hear from people who’ve seen how these things play out in real life.
And honestly, out of the 5 things I keep hearing, from people who know how to move intelligently, this is probably the best piece of advice.
Get advice before you report, not after things go wrong.
This is the biggest one.
The people who handle this best do not wait until a review letter lands.
They speak to a welfare rights adviser, benefits specialist or trusted support organisation before making big moves.
Not because they are doing anything wrong.
Because they understand that wording matters, timing matters and evidence matters.
The honest truth is this:
Trying work should be safe.
People should not be punished for testing their capacity.
But until the system actually protects people properly, the safest move is not fear.
It is preparation.
LCWRA 2026
From 6 April 2026, LCWRA has two monthly rates.
The lower LCWRA amount is £217.26 per month.
The higher LCWRA amount is £429.80 per month.
You may get the higher amount if you reported your health condition before 6 April 2026, were already getting LCWRA before that date, meet the severe lifelong condition criteria or are nearing the end of life.
If you are part of a couple and both partners qualify for LCWRA, only one LCWRA amount is paid, and the higher amount applies if one partner qualifies for it.
There is no single safe income figure that applies to everyone.
Your position depends on your household, housing support, children, health status, work allowance, UC taper, self-employment rules and any deductions.
Two people can both receive Universal Credit and PIP, but have completely different safe income levels.
One person may receive housing support.
Another may not.
One person may have children.
Another may have LCWRA.
One person may be employed.
Another may be self-employed and close to the Minimum Income Floor.
The Confidence Reclaim Starter Pack calculator helps you check your own position before increasing income.
That is safer than relying on a generic number.
From 6 April 2026, the Universal Credit two-child limit ended.
Universal Credit can now include a child amount for every child you are responsible for, not just the first two.
This can change the safe income calculation for larger families, but the benefit cap and other deductions may still affect the final amount paid.
Important for larger households:
Even where extra child amounts apply, the benefit cap may still limit the total amount paid.
If you have several children, housing support or a high UC entitlement, check whether the benefit cap affects your final award.
Universal Credit tapering is gradual.
But the experience can still feel steep.
If your earnings rise above your work allowance, your UC reduces as your earnings increase.
You may still be better off overall, but the extra income may not feel as large as expected.
This is why the phrase “benefits trap” resonates with so many people.
You earn more.
Then UC adjusts.
You keep some of the extra money, but not all of it.
The answer is not to avoid earning.
The answer is to plan the increase.
A sudden jump can create pressure if you have not checked your assessment period, housing support, deductions, tax position, self-employment rules or LCWRA status.
A gradual increase gives you time to see what happens.
It lets you test your numbers before you rely on the income.
Your safe income can change depending on:
This is why quoting one fixed number can be misleading.
One person may have a work allowance.
Another may not.
One person may receive housing support.
Another may not.
One person may have LCWRA protection.
Another may be in a waiting period.
One answer cannot safely cover all of those situations.
The safer approach is to calculate your own position.
A proper income plan does not just ask:
“How much do I get now?”
It asks:
“What happens if I earn this amount?”
That is a different question.
You need to know:
This is where a personal planner becomes useful.
It turns a vague fear into a number you can work with.
Generic benefit calculators can give a useful starting point.
But they cannot always show the emotional and practical journey of building income safely.
The Confidence Reclaim Starter Pack calculator is designed for people who need more than a snapshot.
It helps you test your income before you act.
It shows your safe monthly income.
It converts that into a weekly equivalent.
It estimates how much UC may reduce.
It shows the real gain from extra earnings before tax and NI.
That matters because Universal Credit is assessed monthly, but many people think weekly.
The calculator helps bridge that gap.
It keeps the planning simple without pretending the rules are simple.
Income Planning For Disability Benefits
A fixed figure can feel reassuring.
But it can also be wrong for your situation.
Some people have a work allowance because they have children or limited capability for work.
Some people do not.
Some people receive housing support.
Some people do not.
Some people have deductions that change their final award.
Some people are self-employed and may need to consider the Minimum Income Floor.
So the safest public guidance is:
Use your own numbers.
Check your own UC position.
Treat the calculator as a planning guide, not a legal decision.
If you are unsure, speak to your UC adviser or a benefits adviser before making a major change.
The safest way to build income is gradually.
That does not mean staying small.
It means growing with checkpoints.
Step 1: Know your current benefit position
Before changing income, check what you currently receive.
Look at your UC statement.
Check whether you have a work allowance.
Check whether you receive housing support.
Check whether you have LCWRA, LCW, child elements, carer elements or deductions.
If you receive PIP, check your award letter and review date.
Do not build a plan around memory.
Build it around documents.
Step 2: Use the calculator before increasing income
Before increasing hours, rates or self-employed work, enter your details into the CRSP calculator.
Check:
This gives you a clearer starting point.
You are not guessing.
You are checking.
Step 3: Start with a small test
A first step does not need to be dramatic.
Small income can still build confidence.
A small test helps you see how earnings feel, how reporting works and how UC responds.
The goal is not to rush.
The goal is to build proof.
Step 4: Track your UC assessment period
Universal Credit is calculated monthly.
The date you are paid can affect which assessment period the income lands in.
This matters if you are paid early, paid late, paid twice in one month or receive a one-off payment.
Keep records.
Check statements.
Report changes promptly.
Step 5: Build a buffer before scaling
A financial buffer gives you room to absorb delays, reassessments or unexpected payment changes.
A three-month buffer is a strong protection before scaling income further.
If that feels impossible, start smaller.
Even a small buffer is better than no buffer.
The point is to reduce panic.
Most benefit problems are not caused by earning itself.
They are caused by poor timing, missing reports, misunderstood rules or relying on the wrong number.
These are the mistakes to avoid.
Universal Credit is assessed monthly.
If your income changes, that change can affect your award.
Do not assume the system will always pick everything up correctly.
If you start work, increase hours, take on a contract, receive a one-off payment or change your self-employed income, keep records and report what you need to report.
Late reporting can lead to overpayments.
Overpayments can reduce future UC payments.
That can create the exact instability you were trying to avoid.
The safer rule is simple.
Report changes promptly.
Keep proof.
Check your next UC statement.
Self-employment is not treated the same as employed work.
If you are employed through PAYE, earnings are usually reported through HMRC’s real-time system.
If you are self-employed and claiming Universal Credit, you normally need to report your income and allowable business expenses each month through your UC journal.
This is where many people get caught out.
After the self-employment start-up period, the Minimum Income Floor may apply.
That means Universal Credit may treat you as earning an assumed level of income, even in a month where your actual profit is lower.
This can reduce your UC more than expected.
You may be eligible for a 12-month start-up period if you are self-employed.
During that period, your monthly earnings are normally used to work out your UC and the Minimum Income Floor does not apply.
Your work coach can confirm whether you qualify for a start-up period.
That first year can feel manageable because UC is looking at your reported self-employed profit.
But once the Minimum Income Floor applies, the calculation may change.
This does not mean self-employment is unsafe.
It means self-employment needs planning.
Before relying on self-employed income, check:
The CRSP calculator can help you understand UC taper and safe income planning.
But self-employed claimants should also check the MIF position with their UC adviser or a benefits adviser before scaling.
PIP is not means-tested.
That does not mean it is permanent.
Your PIP award is based on assessed needs.
If your condition improves, your needs change or your work activity appears inconsistent with your award, DWP may ask questions at review.
The safest approach is not to avoid working.
It is to keep your evidence accurate.
Keep medical records.
Keep notes of support needs.
Keep evidence of adjustments.
Keep a copy of your award letter.
If you are unsure whether a work plan could affect how your needs are understood, get advice before relying on that income.
Not everyone has a UC work allowance.
This is an important point.
A work allowance usually applies if you have children or limited capability for work.
If you do not have a work allowance, your UC may reduce as soon as earnings are counted.
This is why fixed income advice can be risky.
If an article says “you can earn up to this amount safely,” but you do not qualify for that allowance, the advice may not apply to you.
Use your own calculator result.
Even if the numbers look right, timing can still create pressure.
Payments can be delayed.
Reviews can take time.
Assessment periods can produce unexpected results.
Self-employed income can fluctuate.
A buffer gives you room to breathe.
The goal is not to build income at any cost.
The goal is to build income without creating a crisis.
Leaving benefits entirely is a major step.
The right time is not simply when your income first looks promising.
It is when your income is stable enough, consistent enough and high enough to replace the support you may lose.
That calculation is personal.
A clean transition should happen from strength, not pressure.
If you are building income gradually, your goal is not to escape benefits overnight.
Your goal is to become less dependent on them safely.
Transition readiness checklist
Before making a major income jump or moving away from benefit support, check the following:
✓ Your earned income has been stable for several months
✓ Your monthly income comfortably covers essential costs
✓ You have checked your UC taper position
✓ You understand whether you have a work allowance
✓ You have checked whether the Minimum Income Floor applies
✓ You have reviewed any linked benefits
✓ You have checked your PIP award conditions and review date
✓ You have built a financial buffer
✓ You have confirmed your reporting duties
✓ You have spoken to a benefits adviser if your situation is complex
This checklist is not there to slow you down.
It is there to stop one mistake undoing your progress.
Check your own safe income before you scale
Generic figures can be misleading.
Your safe income depends on your housing support, household, children, health status, work allowance and UC position.
The Confidence Reclaim Starter Pack calculator helps you check your own monthly safe income, weekly equivalent, UC reduction and real gain before you increase work or self-employed income.
Use it before you scale.
Earning income does not directly reduce PIP because PIP is not means-tested.
You can earn income through employment or self-employment and your PIP is not reduced simply because you earned money.
But PIP can still be affected indirectly if your work appears inconsistent with the needs described in your award.
If your condition, care needs or daily living ability changes, that may affect your award at review.
The Universal Credit work allowance is the amount some claimants can earn before UC starts to reduce.
Not everyone has a work allowance.
It usually applies where someone has children or limited capability for work.
If you do not have a work allowance, your UC may reduce as soon as earnings are counted.
This is why your personal calculator result matters more than a general figure.
Universal Credit does not use the old 16-hour rule in the same way.
UC is based mainly on income and household circumstances.
What matters is how much you earn and how those earnings affect your UC calculation.
If you are still on ESA or transitioning from older benefits, hours rules may still apply.
Check before making changes.
If you earn above your relevant work allowance, UC usually reduces through the taper.
The usual taper is 55p for every £1 above the allowance.
That means you still keep some of the extra earnings, but your UC may reduce.
The calculator helps show what that looks like in your own situation.
Yes, but self-employment has extra rules.
If you are self-employed and claiming UC, you normally need to report income and allowable expenses each month through your UC journal.
After the start-up period, the Minimum Income Floor may apply.
This means UC may treat you as earning an assumed amount, even if your actual profit is lower that month.
That can change your safe income planning.
Use the CRSP calculator to understand taper impact, but get specific advice on self-employment rules before scaling.
The Minimum Income Floor usually does not apply during the self-employment start-up period.
That start-up period is commonly 12 months.
After that, UC may assume you earn a certain level from self-employment.
This can reduce UC more than expected in a low-profit month.
If you are approaching the end of your start-up period, check your position before making income plans.
If you have LCWRA and earnings reduce your UC to zero, there may be protections that allow you to return within a limited period without a fresh Work Capability Assessment.
The details depend on your situation and timing.
Do not rely on this without checking your own claim.
If you are on ESA rather than UC, the rules are different.
Get advice before starting work if returning safely is a major concern.
Yes, if possible.
A buffer protects you if payments are delayed, UC changes more than expected or a review takes time.
Three months of essential costs is a strong target.
If that feels too much, start smaller.
The important thing is to build some protection before relying on higher income.
No.
The calculator is a planning tool.
It helps estimate UC taper impact, safe income and real gain.
It does not calculate every exception, tax, NI, surplus earnings, sanctions, capital rules, self-employment complexity or every deduction.
Use it to plan more safely.
If you are unsure, check with your UC adviser or a qualified benefits adviser
Building income while receiving disability benefits can feel frightening.
But fear usually grows in the gap between not knowing and needing to act.
The safest path is to close that gap.
Check your award.
Use your calculator.
Test small steps.
Report changes.
Keep records.
Build a buffer.
Get advice where the rules are complex.
You do not need one general answer.
You need your answer.
That is what the Confidence Reclaim Starter Pack calculator is designed to help you find.
Last reviewed: May 2026.
Benefit rules change.
Check current GOV.UK guidance or speak to a qualified benefits adviser before making major income decisions.
Income Planning For Disability Benefits